All Categories
Featured
Strategies to Maximise Foreign Investment Potential in 2026
Frameworks for Capital Diversification in 2026 Global Mar...


Key Financial Trends Across the GCC
Table of Contents
With globalization in retreat, regional blocks and new rules in trade, security and currencies emerge, making it key to invest with durability and geographical/strategic diversification. We go into a more relentless inflationary regime due to structural factors and public deficit, so inflation ends up being a main axis to protect long-lasting genuine returns.
2026 demands. however with shorter maturities, ought to offer attractive returns with manageable danger. Neutral on sovereign debt from emerging markets and.: AI continues to be an essential motorist (higher diversity advisable). We continue to choose Asia, with among our primary convictions.: pressure continues on oil and gas prices, benefiting Europe.
European currencies might extend their gains, with the staying as a. The moderately as the effects of President Trump's trade program dissipate and the boom that indicates financial investment in AI.: Japan consolidates exit from deflation with reforms and more nominal growth; China continues to be weighed down by real estate/consumption in the brief term, however with a structural engine in AI and technology.: neutral stance in developed stock due to stabilize between AI advantages and valuations/tariffs.
Future-Proofing Middle East Portfolios against 2026 TrendsCapital Diversification Blueprints for a 2026 Economy
The primary risks are a possible bubble/disappointment in AI returns, political sound in the United States and geopolitical hotspots (Russia-Ukraine and others).: retail entry continues in personal and AI continues to permeate portfolios. Rotation and IPOs improve but view out for tension in venture capital/direct lending, while hedge funds can record alpha in volatility.
Evaluating GCC Capital Incentives vs Emerging MarketsThe ECB would adopt a more cautious stance, balancing German financial stimulus and dangers on work and intake. The: spreads stay very tight, but backed by high corporate earnings, high margins and low default rates. The environment prefers: returns are anticipated to be aligned with present yield levels, mainly supported by the carry.
In the United States, a is preferred, combining short period with exposure in the 710 year variety. In investment grade, threat premium compression prefers a rotation from subordinated to senior financial obligation. If there is a bubble, it is not in the technology itself, however in the appraisals of a specific group of companies.
Emerging market financial obligation, backed by lower financial obligation levels, solid principles and less dollar reliance, uses appealing alternatives to developed market assets.: they are not a passing fad. Their growth is driven by sustaining structural factors. The healing is underway and development will speed up accessibility.: stands apart for much better risk-adjusted efficiency and better credit quality compared to the US.
However, after the last Fed rate cut, it is a mystery to know the level to which rates will drop in 2026.2026 will be beneficial for equities, and in set earnings it will be necessary to diversify and be selective., due to stimuli and accommodative financial policy. Amongst them, he sees more prospective in Japan and emerging markets due to assessments.
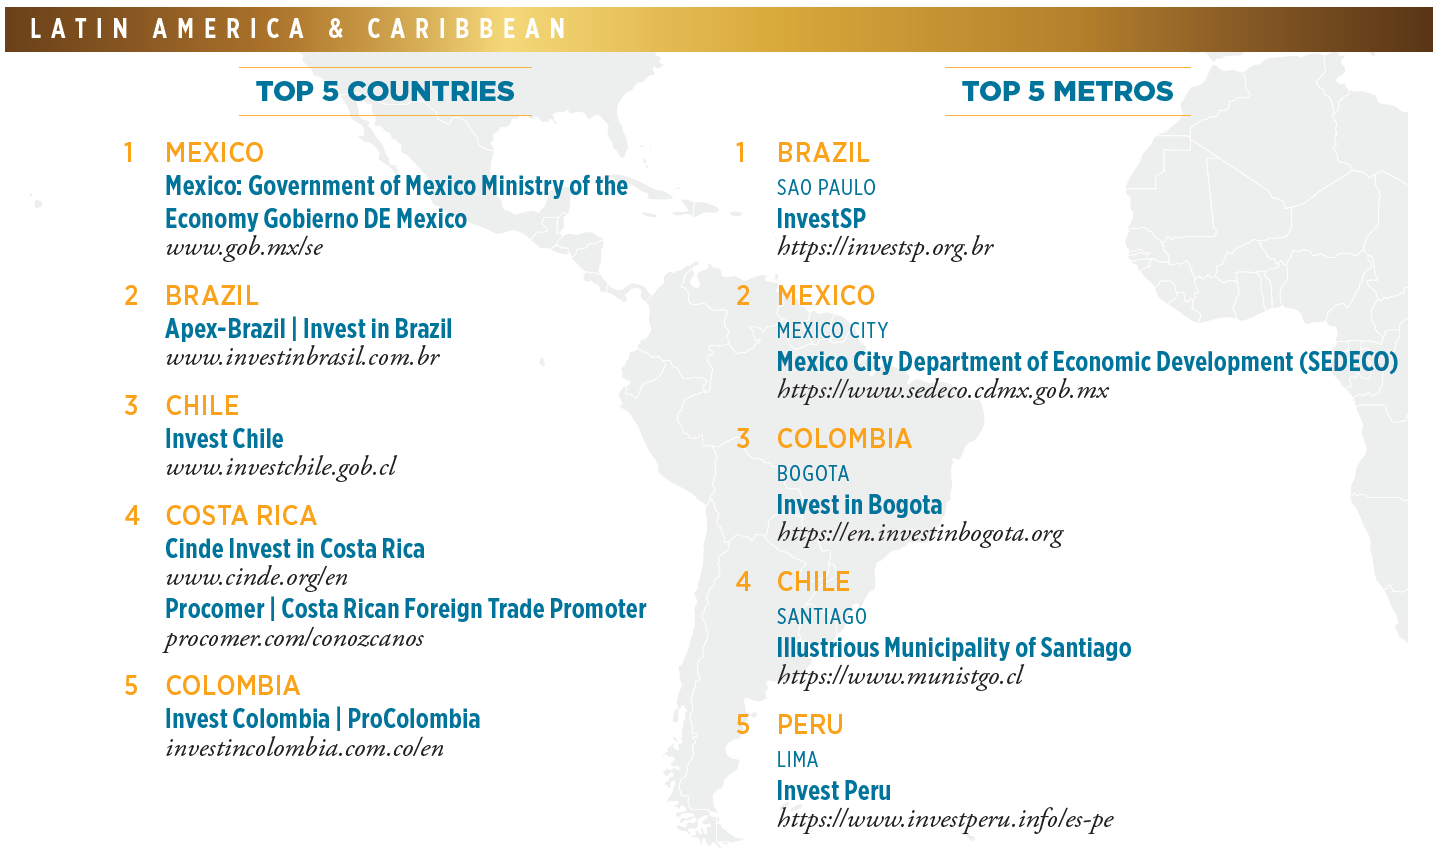
Critical Tips for Entering 2026 Overseas Investment Climates
The of the year that will have the most influence on the marketplaces will be Donald Trump, tariffs, reserve banks, AI, and geopolitics.: in the United States, two-speed development is expected to continue 2026, remaining below its 2% capacity. In the Eurozone, the financial recovery is acquiring momentum, driven in specific by financial investment plans in Germany.
In the United States, the potential customers for long-term rates of interest stay more unsure. Present fundamentals support credit, which will be a favored bond asset for the next year. However, this trend still depends on the ability of companies to fulfill expectations. In our base hypothesis, we visualize a that would be a repetition of the 2017 conditions.
There is a risk of a drop for the.: sustainability themes evolve and focus on adjusting to. In the medium term, there is concern about the boost in public financial obligation levels and the possibility of speeding up inflation. There is a perceived.There is prospective in the and good prospects for.: offers much better characteristics and higher genuine returns than the financial obligation of developed markets.: can be considered an essential location where cyclical and structural forces align to create opportunities.
Benefits of Diversified Capital Allocation in 2026
remains an important property in any allowance due to its capability to generate return, bring and capitalization. Specifically, in the field, we think that the basics of providers stay solid. We continue to bank on developing portfolios around high yield providers with affordable financial obligation levels and returns.Selection of instruments with lower ratings, especially CCC.: the fundamentals of the European banking sector remain solid.
Within the banking sector, it generally focuses on.Very mindful to the possible contagion of to fixed earnings markets.: opportunities specifically in, sectors that provide attractive assessments and will benefit as quickly as the current market distortions normalize; as well as in. continues to be another appealing investment style.

Latest Posts

Strategies to Maximise Foreign Investment Potential in 2026
Frameworks for Capital Diversification in 2026 Global Markets
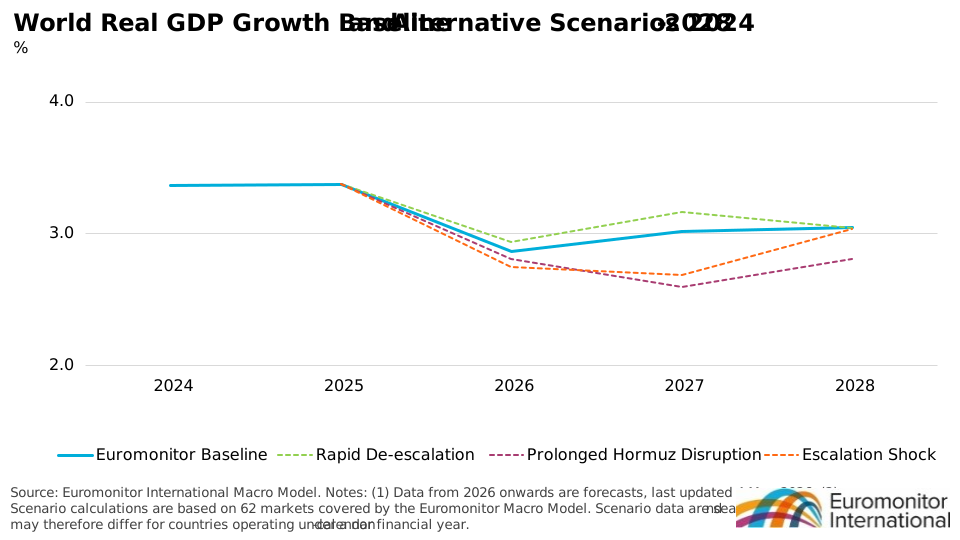
Comparing GCC Capital Climates vs Global Peers